How to Sell Your Business for Maximum Value.
Get exit-ready, understand what your business is really worth, get in front of serious buyers, and sell confidentially with guidance from Chantel Ray Finch.
Get Your Free Business EvaluationBefore You Price It: Start With What You Need
The first thing to do before selling your business has nothing to do with the business. It starts with you. Figure out what you need personally before you focus on what the business might be worth. That sounds backwards, but here's why: if you want to sell because you want to retire, the first place to start is the retirement resources you already have. Compare the retirement income you need against what your savings and investments can already support, and see whether the business can realistically cover the rest. And never assume the sale of your business alone will fund your retirement.
Skip that step and you fall into a trap called aspirational pricing. You put the business up for sale, then you figure out what you need to retire, and then you realize you have to sell for a certain number or you can't retire. Your business's value has nothing to do with what you need. It's set by what buyers will pay.
Here's the other thing most owners miss: retirement is only one reason people sell. The others are burnout, boredom, health, divorce, and relocation. Big life changes. And of all those reasons, the only one people actually plan for is retirement. That's the whole argument for keeping your business ready to sell at any time, because you don't know when one of those conditions will erupt and force you to get out faster than you expected. The best exit options belong to owners who still have time. Ideally you're preparing three to ten years before you ever think you'll want to sell, and it's never too early to know your number.
Knowing your number is exactly where your free business evaluation comes in.
Step 2 of 2 — Fill information
…and learn how we'll position, market, and sell your business in as little as 90 days — connecting you with qualified buyers
and negotiating the deal on your behalf.
During this call, we will:
Analyze Your Business From a Buyer's Perspective
Uncover the value gaps, owner-dependency risks, and deal blockers that could cost you money at the negotiating table — before buyers ever see them.
Build Your Personalized Exit Roadmap
Get a clear, step-by-step plan showing exactly how we'll price, position, and market your business to attract serious, qualified buyers — and sell at the highest possible multiple.
Provide a Risk-Free Consultation
It's 100% free — no pressure and no obligation to move forward. Just real, actionable clarity on what your business is worth and what it will take to get it sold.
Before You Sell Your Business:
You've worked hard over the course of your entrepreneurial career. You've put blood, sweat and courage into your business. Who knows it better than you?
But here's what most owners don't know: selling a business is a complex process, and the mistakes are expensive. Price it wrong and you leave money on the table. Present it wrong and you scare off perfectly good buyers. Let word get out and you spook your employees, customers, and vendors before you ever see an offer.
My name is Chantel Ray Finch. My husband and I have built over 16 companies and sold four of them for multi-millions of dollars across industries including finance, service, real estate, and brick and mortar. We've sat on both sides of the table, and we know exactly what buyers actually pay for.
So where do you get expert help selling your business without paying a dime upfront?
Right here, actually.
How To Sell My Business Myself is designed to help business owners sell for maximum value, with no upfront fees, ever. We don't get paid unless your business sells.
And we're so confident in our process that we guarantee to get you an offer on your business within 90 days. If your business qualifies for our program and we accept your listing, and we do not present you with a qualified offer within 90 days, you won't owe us a commission.
It all begins with your free professional business evaluation.
You Have More Exit Options Than You Think
Most owners think selling means one thing: list it and wait for a stranger to buy it. In reality you have several paths. An outside sale. An inside sale to employees or management. Family succession. A staged buyout. Or liquidation. Every business owner needs an actual exit plan, not just a vague idea, and listing your business for sale is not the same thing as having one.
Selling to an employee is a real option, but it comes with its own dynamics around financing and readiness. Family succession is not automatically the best option just because it feels natural. A staged buyout, where you sell to somebody one piece at a time, can be one of the most lucrative outcomes: the buyer works with you inside the business and develops their own insider advantage, which reduces their risk, and if the business is growing, each successive piece can sell for a higher price. And in certain cases, liquidation genuinely beats selling, which we'll get to below.
What makes any of these paths possible is having a sellable business in the first place. A sellable business has transferable cash flow, not just owner effort. It comes down to where the goodwill lives. If it lives with you personally, it doesn't transfer. And the difference between a job, a hobby, and a real business? Cash flow. Specifically, how much seller's discretionary earnings you actually have after you strip out the noise.
STEP 1: Your FREE BUSINESS EVALUATION
First, watch my YouTube channel where I share real deals, real numbers, and the lessons my husband and I learned building over 16 companies and selling four of them. You'll get to know more about me and how we look at businesses the way buyers do. Best of all, it's totally FREE.

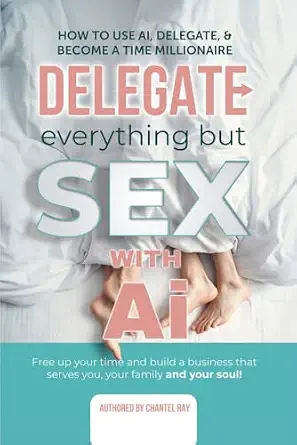
Second, download a FREE chapter of my book, Delegate Everything But Sex with AI. You'll learn how to master delegation, reduce owner dependency, and build the systems buyers pay a premium for, which are exactly the things that increase what your business sells for. It's the same playbook we used to build over 16 companies and sell four of them.
Third, request your free professional business evaluation. We normally charge $5,000 for this process, but right now we're doing it completely FREE because we have so many qualified buyers actively looking for businesses to purchase. Fill out the short form and our team will reach out to schedule it.
Get Started FREEIf you're ready to find out what your business is really worth, you're ready for Step 2.
STEP 2: PRICING GUIDANCE
The worst that can happen is you over or under price your business. Overprice it and it sits on the market until buyers assume something's wrong. Underprice it and you hand away years of hard work at a discount.
Value depends on your cash flow, recurring revenue, systems, owner dependency, and industry multiples. We'll give you a realistic picture of what your business could sell for today, a reasonable asking price we can defend to buyers and their bankers, and exactly what would increase that number if you have time to prepare the business for sale.
What Buyers Are Actually Paying For
When someone buys a small business, they're acquiring a cash flow. That's it. Not machinery, not inventory, not any of that other stuff. They're buying it because they want to make money with it, and if you've been successfully making money with it, that's what they're interested in. In this industry, that gets expressed as SDE (seller's discretionary earnings) or EBITDA. That's the format businesses are sold in.
That's also why normalizing your financial statements matters. It means restating your financials to show what the business actually earns for an owner, adding back things like personal expenses run through the business, non-recurring items, and non-market compensation. And here's a hard truth: nobody cares what you invested in the business. Buyers care about the SDE and the EBITDA. Buyers don't pay for potential either, not if they're paying attention. Unless the potential is very believable and very close to being realized, every buyer will look at you and say, "If you could have made that profit, why didn't you already?" The proof is in the pudding.
How much does owner dependence hurt value? Tremendously. Industry rules of thumb and multiples are fine for a rough ballpark, but you really need to dig in with someone who has experience valuing businesses, and it's worth refreshing a valuation every couple of years as a running scorecard. One more note: if your business owns real estate, those are two separate investments that get evaluated separately, except in businesses like special care homes, motels, and mini-storage where the real estate and the business are essentially one thing. And if your books include personal expenses or unrecorded sales to save taxes today, know that it costs you at sale time. Profits buyers can't document get discounted, and it usually means doing a lot more seller financing.
Goodwill, in Plain English
Goodwill is the difference between the value of the tangible assets inside the business and the value of the business as a going concern. The assets have to be employed in a way that generates a cash flow worth more than the assets themselves. A well-managed, highly profitable business with low capital requirements has an easier time developing goodwill: think of a house-cleaning service that owns a few vacuum cleaners versus a foundation contractor who's invested in dump trucks, form sets, and backhoes.
Goodwill shows up as real, everyday things. A clothing brand with 100,000 real followers ready to buy. A detailing shop with 500 five-star reviews standing next to a new one with zero. A plumbing company where the phone already rings every day. A coffee shop where hundreds of people come in every week out of habit. A pizza restaurant where you get the recipes, the training, the supplier relationships, and the knowledge of how everything works. The easiest explanation: if I give you $100,000 worth of equipment, you have equipment. If I give you that same equipment plus a business that already has customers, employees, reviews, a reputation, systems, and makes money every month, you have something worth much more. That extra value is goodwill.
Negative Goodwill: When the Stuff Is Worth More Than the Business
Negative goodwill is when the value of your cash flow is worth less than your tangibles. Picture a trucking company with $2 million in trucks that makes $80,000 a year. Would you pay $2 million to earn $80,000? No. You'd buy the trucks and skip the business. Or a diner in a $900,000 building making $40,000 a year: a buyer will happily pay for the building, and not one extra dollar for the diner. Or a machine shop with $1.5 million in machines that barely breaks even. The buyer can get those same machines at auction without taking on the payroll.
So why would anyone sell for less than the assets are worth? Because closing costs money. Imagine that machine shop shuts down instead: severance for twelve employees, three months of rent with nobody working, auction fees, and the machines selling for half their value. The owner walks away with $600,000. A buyer offered $900,000 for the whole thing. Less than the assets were worth, and still the better deal. The simple version: goodwill is when the business makes the stuff worth more. Negative goodwill is when the business makes the stuff worth less. If your cash flow is worth less than your equipment or real estate, you don't have a business to sell. You have assets to sell, and your exit plan needs to look completely different. Your free evaluation tells you which side of that line you're on.
STEP 3: BUYER READINESS
My team and I prepare your FREE 8-Page CIM (Confidential Information Memorandum), the professional sales package for your business, so that when you meet the right buyer you can proceed and make a deal while the interest is high. Your CIM can include an overview of your business, financial performance, products and services, operations, employees, growth opportunities, and competitive advantages.
Buying or selling a business is both an emotional and logical exercise. Presenting information at the wrong time can ruin a deal with an ideal buyer, so we manage exactly when and how buyers see it.
We create this professional 8-page CIM for you completely FREE.
What Makes a Business Attractive to Buyers
Clean financials. Documented processes. A capable team. Reasonable working capital. And cash flow that doesn't depend on you personally. Reducing owner dependence comes down to implementing systems and processes and delegating authority to the right people in your company, and yes, standard operating procedures help because they directly address the owner-dependence question. There are really two teams to think about: a team of advisors, because you'll be dealing with the proceeds of the transaction and need to handle them right from a tax and investing point of view, and the team inside your business, which needs the right people, training, and processes to survive your departure.
Should you improve profits before selling, even if it means paying more tax? Usually, yes. Always try to improve your profits. Some owners depress profits through shady tactics to save on taxes, and here's what happens: if buyers can't see declared profits that are documented, recognizable, reviewable, and auditable, they discount them. You end up with a business that can't get a bank loan, and you end up financing the whole transaction yourself. You can reduce your tax burden today and pay for it in the deal structure, or earn more, pay more tax today, and get a stronger exit with more money at closing.
And how far in advance should you clean things up? Buyers spend the most time on the two years prior to the deal, but life doesn't give you two years' notice. Burnout, health, divorce, relocation: none of them schedule themselves. Clean things up right now, so your business is always in a state of high saleability and the option to exit stays open.
Working Capital: The Part That Trips Owners Up
Working capital is the cash a business needs sitting in the bank just to operate. Payroll on Friday. Rent on the first. Inventory you buy before the customer pays you. Invoices that take 45 days to collect. Picture a landscaping company: payroll is $40,000 every two weeks, fuel and materials run $15,000 a month, and customers pay 30 to 60 days after the job. The business always has about $100,000 out the door before money comes back in. That $100,000 is the working capital.
Here's what trips people up: the cash sitting in the business bank account belongs to the seller. It does not count toward the sale price. When you sell, you're selling the equipment, the customers, the name, the systems, and the cash flow. The money in the checking account is yours, and yes, you can pull out excess cash before you sell. What you can't do is confuse cash with the business and call a pile of cash the value of the company.
It also means the buyer has to bring their own working capital, on top of the purchase price and the down payment. Imagine a buyer approved for a $1 million SBA loan, but the business needs $500,000 in working capital and after the down payment and closing costs the buyer only has $300,000 left. That's a red flag. Two bad months, a late-paying customer or a slow season, and there's nothing left for payroll while the bank still gets paid every month. Lenders look at working capital as hard as they look at the purchase price, and so should you. Know your number, be clear about what you're selling and what you're keeping, and qualify your buyer on the cash they'll have left to run the business, not just the loan they got approved for. A buyer who can afford the business but can't afford to run it is a buyer who hands it back to you in a year.
STEP 4: BUYER SELECTION
You can't let it become public that the business is for sale. Confidentiality protects your relationships with employees, customers, and vendors, so we market your business confidentially through our network of vetted buyers and investors, targeted outreach, and professional listing channels, while our team manages inquiries for you to filter out all but the truly qualified buyers.
Every prospect is screened for financial capability and seriousness, and required to sign an NDA, before they ever see any identifying details about your company. You only spend time on buyers who can actually close.
Why Confidentiality and Buyer Vetting Matter So Much
A business's goodwill can be destroyed if people find out it's for sale. It creates problems for you as the owner and for the buyer coming in. That's why businesses are marketed through blind listings that describe the company without identifying it, non-disclosure agreements, and a vetting process before anyone sees real details, and why employees usually find out later in the process, at the right moment, with a clear plan. There can even be statutory and legal reasons employees need to be brought in, which is exactly why you want someone who has been through this many times guiding the sequence.
The buyer-facing centerpiece is the confidential business profile, the sales brochure for your business. It tells the story of the company, why it's great, and why somebody should buy it, built custom from your actual operating performance with the financials alongside the narrative. The number one reason good businesses don't sell, or take too long to sell, is that nobody puts effort into this. A one-page summary stapled to some tax returns is not a presentation that sells the merits of your business. That's exactly what your free 8-page CIM exists to fix.
Then there's vetting. There are listing sites and brokerages where you click inquire, you're automatically fed an NDA, you sign it, and the whole business package gets delivered to you automatically. Financial statements, memorandum, everything. Nobody has checked who you really are. Nobody asked for ID. You could be a direct competitor. Automation without real vetting creates huge risk for business owners, and it's why every prospect here is screened for financial capability and seriousness, and met, before they ever see identifying details. Because at the end of the day, buyers are really looking for three things: clear cash flow that's believable, risks that are clearly understood, and confidence that the business will keep generating that cash flow after you leave.
Can you sell without a traditional broker and still get a great result? Yes, as long as every broker function still gets done: the valuation, the business profile, the confidential marketing campaign, and the buyer vetting. That's precisely what this program handles for you, with no upfront fees, and no commission owed unless your business sells.
STEP 5: NEGOTIATION & CLOSING
You may never have sold a business before. We've built, scaled, and sold our own, and we've stood side-by-side with owners through the entire process. We negotiate on your behalf to maximize what a buyer is willing to pay, not just to get a deal done, and we guide you through due diligence all the way to the closing table.
So what are you waiting for? A $5,000 business evaluation, FREE. An 8-page professional CIM, FREE. No upfront fees, and we guarantee to get you an offer within 90 days. Start today with your free business evaluation.
Get Your Free Business EvaluationPrice, Terms, and the Power of Seller Financing
What matters more, the price or the terms? Often it's the terms. Buyers will agree to a much higher price if you finance part of it at a low interest rate over a longer period. There are dials on this machine, and when you adjust one, something else has to move too. Do it right, with the right qualified buyer, and the sale can become an investment that yields far better returns than taking all cash and parking it in a short-term deposit.
Seller financing is common in small business sales because many businesses include goodwill that banks won't fully finance, or carry risk factors like customer concentration that scare banks off. Seller financing bridges those gaps. It doesn't mean you're taking too much risk; it means you're sharing the risk. You're making an investment in the buyer, which is exactly why finding the right one matters: someone coachable, someone who will succeed as the operator. Buyers and their banks love seller financing because it demonstrates the seller has confidence in the buyer, the market, the industry, and the business. The owner knows the business better than anyone, and financing part of the deal puts that knowledge behind your confidence. Flatly refusing to finance sends the opposite signal, and buyers hear it loud and clear. Without a note of material size, the only knob a buyer has left to turn is the price. Down.
A few deal terms worth knowing before you see them in an offer. An offset clause in a seller note says that if something you claimed turns out to be false after closing, the buyer can offset their damages against what they owe you, which is exactly why honest sellers shouldn't fear one. A bank putting your seller note on standby means you wait until the bank allows the buyer to pay you; it usually only happens with heavy leverage, and it can be a sign your buyer is under-capitalized. An earn-out is a payment after closing based on future performance: if you're claiming the business is about to grow, an earn-out is you putting your money where your mouth is, and they can last years. And on closing day, remember the cash at closing is whatever the buyer puts in plus what they borrowed, and some of their total investment may go to their own operating capital or required renovations rather than to you. The offer will show exactly what you're being paid.
After the Closing Table
Stay long enough to help the buyer succeed, but not so long that the roles get confusing or it starts to look like a job. If you're asked to stay and work, there should be a salary attached. If you're staying to teach, it usually tapers: a month full-time alongside the buyer, then half days, then a half day every second week, then phone calls. Your transition plan should cover whatever the buyer needs to learn to do your job as the owner, written down, because the owner is the expert and rarely realizes how much lives only in their head. Consulting after the sale can ease the handoff and create extra income when it's clearly defined against training, including whether and where you can consult for others.
Transition matters even after you've been paid, because for the deal to succeed, especially with a seller note or an earn-out, you need the buyer to succeed. The note binds both parties' interests together: it gets you a higher price, lets the buyer share risk with you, and gives them confidence you'll train them well. Most disputes after a sale trace back to poor disclosure, weak transition planning, unclear expectations, and undocumented assumptions. And protecting your legacy comes down to choosing the right buyer, one who buys into that legacy and can afford it, without a debt burden so heavy they can't pay for the things you want the business to keep doing.
By the end of the process, your buyer, your employees, and your customers should all feel one thing: confidence. That's the guiding light through every decision. Because if they don't feel it, employees leave, customers drift, the buyer struggles to pay their financing, and you don't collect your note. Start with what you personally need, keep the business saleable at all times, remember that buyers pay for cash flow they can see and believe, use terms and seller financing as tools instead of threats, and aim everything at confidence.
Here's Everything You Get:
"A professional business evaluation, a $5,000 value, completely FREE. We review your business the same way a serious buyer would: your financials, your operations, what it's worth, and anything that could affect the sale."
"A professional 8-page CIM, completely FREE. Your Confidential Information Memorandum is the sales package that gives qualified buyers everything they need to understand your company and get serious about making an offer."
"A guaranteed offer within 90 days. If your business qualifies for our program and we accept your listing, and we do not present you with a qualified offer within 90 days, you won't owe us a commission."
You didn't work hard all these years to leave money on the table.
With the right preparation, the right buyers, and the right team negotiating on your behalf, you can sell your business for what it's truly worth. Keep more of what you've worked so hard to build.